India Car Sales September 2026: Dispatches Rise 21% to 4.58 Lakh Units; Maruti Suzuki Leads, Tata and Mahindra Follow
India’s passenger vehicle market recorded strong year-on-year growth in September 2026, with Maruti Suzuki maintaining its leadership, Tata Motors securing second place, and Kia registering robust growth. Nissan emerged as the fastest-growing manufacturer on a percentage basis.
India’s passenger vehicle industry maintained positive momentum in September 2026, with total domestic wholesale dispatches reaching 4,57,604 units, compared with 3,78,457 units in September 2025. This represents a healthy 20.9% year-on-year (YoY) growth, supported by higher dispatches from several major automobile manufacturers.
On a month-on-month (MoM) basis, dispatches increased by 3.6%, compared with 4,41,576 units in August 2026, indicating continued momentum in the passenger vehicle market.
Maruti Suzuki retained its dominant position with 1,81,838 units and a market share of 39.7%. Tata Motors and Mahindra occupied the second and third positions, respectively, while Hyundai and Kia completed the top five manufacturers.
The September performance also highlighted changing competitive dynamics, with Maruti Suzuki and Kia gaining market share, while several other established manufacturers witnessed year-on-year declines in their share of the domestic market.
OEM-Wise Car Sales in September 2026
The following table provides a detailed comparison of manufacturer-wise passenger vehicle dispatches, including year-on-year and month-on-month performance.
Rank | Manufacturer | Sep'26 | YoY Growth | MoM Growth |
1 | Maruti Suzuki | 1,81,838 | +36.9% | +2.8% |
2 | Tata Motors | 68,810 | +15.3% | +5.5% |
3 | Mahindra | 64,092 | +14.0% | +8.2% |
4 | Hyundai | 57,166 | +10.9% | +5.1% |
5 | Kia | 32,017 | +41.0% | +10.2% |
6 | Toyota | 25,027 | -7.6% | -11.9% |
7 | MG Motor | 8,018 | +19.2% | +6.8% |
8 | Skoda | 6,102 | -8.0% | +8.0% |
9 | Honda | 4,465 | -15.8% | -17.1% |
10 | Renault | 3,399 | -20.3% | +19.6% |
11 | Nissan | 3,300 | +99.8% | -3.7% |
12 | Volkswagen | 2,218 | -20.2% | -2.8% |
13 | Citroen | 900 | +22.6% | -2.9% |
14 | Jeep | 252 | -16.0% | +11.5% |
Total | 4,57,604 | +20.9% | +3.6% |
Maruti Suzuki – 1,81,838 Units | 36.9% Growth
Maruti Suzuki led India's passenger vehicle market in September 2026, dispatching 1,81,838 units, up from 1,32,821 units in September 2025, marking a 36.9% YoY growth and a 2.8% increase over August 2026. Its market share rose from 35.1% to 39.7%, gaining 4.6 percentage points, with the largest absolute increase of 49,017 units among all manufacturers.
Tata Motors – 68,810 Units | 15.3% Growth
Tata Motors ranked second with 68,810 domestic passenger vehicle dispatches, up from 59,667 in September 2025.
The company saw a 15.3% YoY and 5.5% MoM growth. However, its market share dropped from 15.8% to 15.0% due to faster overall market expansion.
Tata led Mahindra by 4,718 units during the month.
Mahindra – 64,092 Units | 14.0% Growth
Mahindra held third place with 64,092 units, up from 56,233 in September 2025, achieving 14.0% YoY and 8.2% MoM growth. However, its market share dropped from 14.9% to 14.0%, indicating growth below the industry average.
Hyundai – 57,166 Units | 10.9% Growth
In September 2026, Hyundai Motor India recorded 57,166 domestic dispatches, up from 51,547 units the previous year, marking a 10.9% YoY and 5.1% MoM growth. Despite higher volumes, Hyundai's market share fell from 13.6% to 12.5%, maintaining its position as the fourth-largest passenger vehicle manufacturer behind Maruti Suzuki, Tata Motors, and Mahindra.
Kia – 32,017 Units | 41.0% Growth
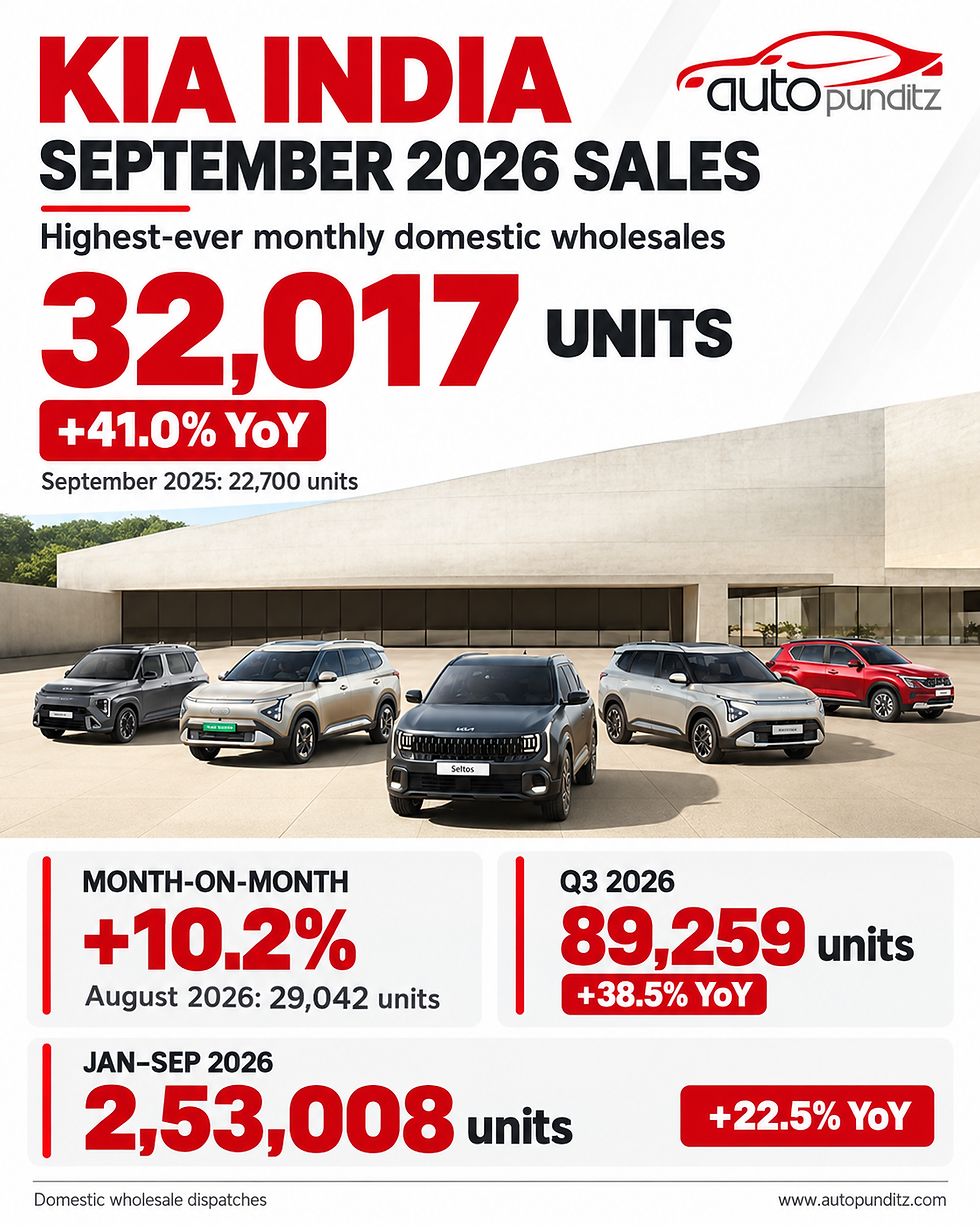
Kia India registered 32,017 units, up from 22,700 in September 2025, achieving 41.0% YoY and 10.2% MoM growth, outperforming the passenger vehicle industry. Kia's market share increased from 6.0% to 7.0%, consolidating its fifth position in the domestic market.
Toyota – 25,027 Units | 7.6% Decline
Toyota dispatched 25,027 units, a 7.6% YoY decline from 27,089 units in September 2025. Monthly dispatches fell 11.9% from August 2026. Its market share dropped from 7.2% to 5.5%, the largest YoY reduction among manufacturers in the data.
MG Motor – 8,018 Units | 19.2% Growth
MG registered 8,018 units in September 2026, against 6,728 units in the corresponding month last year. Dispatches grew 19.2% YoY and 6.8% MoM. However, its market share remained broadly unchanged at 1.8%.
Skoda – 6,102 Units | 8.0% Decline
Skoda reported 6,102 units, compared with 6,636 units in September 2025, translating into an 8.0% YoY decline. On a sequential basis, however, dispatches improved by 8.0% over August 2026. Its market share declined from 1.8% to 1.3%.
Honda – 4,465 Units | 15.8% Decline
Honda recorded dispatches of 4,465 units, compared with 5,305 units in September 2025. The company registered a 15.8% YoY decline and a sharper 17.1% MoM contraction. Its market share decreased from 1.4% to 1.0%.
Renault – 3,399 Units | 20.3% Decline
Renault dispatched 3,399 units in September 2026, compared with 4,265 units a year earlier. Although its year-on-year performance declined by 20.3%, the manufacturer achieved a strong 19.6% month-on-month recovery, the highest sequential growth rate among the manufacturers in the table.
Renault's market share stood at 0.7%, compared with 1.1% in September 2025.
Nissan – 3,300 Units | 99.8% Growth
Nissan saw the highest growth among manufacturers, with dispatches nearly doubling from 1,652 units in September 2025 to 3,300 units in September 2026, marking a 99.8% YoY increase. Despite a 3.7% decline from August, its market share rose from 0.4% to 0.7%, driven by its low base in September 2025.
Volkswagen – 2,218 Units | 20.2% Decline
Volkswagen registered 2,218 units, compared with 2,780 units in September 2025.
The manufacturer recorded a 20.2% YoY decline and a 2.8% MoM decline, with market share falling from 0.7% to 0.5%.
Citroen – 900 Units | 22.6% Growth
Citroen recorded dispatches of 900 units, compared with 734 units in September 2025.
While the company achieved 22.6% YoY growth, monthly volumes declined by 2.9%. Its market share remained at approximately 0.2%.
Jeep – 252 Units | 16.0% Decline
Jeep recorded 252 units, a 16.0% YoY decline from 300 units in September 2025. However, dispatches improved by 11.5% from August 2026, with the market share remaining at about 0.1%.
Market Share Analysis – Maruti Suzuki and Kia Gain Ground
September 2026 witnessed noticeable changes in market share as manufacturers grew at different rates.
Manufacturer | Sep'26 Share | Sep'25 Share | Change |
Maruti Suzuki | 39.7% | 35.1% | +4.6 pp |
Tata Motors | 15.0% | 15.8% | -0.7 pp |
Mahindra | 14.0% | 14.9% | -0.9 pp |
Hyundai | 12.5% | 13.6% | -1.1 pp |
Kia | 7.0% | 6.0% | +1.0 pp |
Toyota | 5.5% | 7.2% | -1.7 pp |
MG Motor | 1.8% | 1.8% | 0.0 pp |
Skoda | 1.3% | 1.8% | -0.4 pp |
Honda | 1.0% | 1.4% | -0.4 pp |
Renault | 0.7% | 1.1% | -0.4 pp |
Nissan | 0.7% | 0.4% | +0.3 pp |
pp = percentage points.
Maruti Suzuki was the biggest market share gainer, increasing its share by approximately 4.6 percentage points. Kia also improved its competitive position with a gain of around 1 percentage point.
Toyota, Hyundai, Mahindra and Tata Motors experienced market share erosion despite some of them recording positive dispatch growth.
This highlights an important distinction: higher sales volumes do not necessarily translate into higher market share when the overall industry is growing faster.
Key Trends from September 2026 Car Sales
Industry growth remained strong: Domestic passenger vehicle dispatches increased by 79,147 units compared with September 2025.
Maruti Suzuki drove a substantial portion of growth: Its additional 49,017 units represented approximately 62% of the industry's net year-on-year increase.
Tata and Mahindra maintained their positions: Both manufacturers registered double-digit growth, although their market shares declined.
Kia outperformed major rivals: Its 41.0% YoY growth was the highest among the top five manufacturers.
Nissan delivered the highest percentage growth: Dispatches nearly doubled, albeit from a relatively small base.
Toyota and Honda faced sequential pressure: Their dispatches declined by 11.9% and 17.1%, respectively, compared with August.
Renault showed the strongest monthly recovery: Its 19.6% MoM increase contrasted with a 20.3% YoY decline.

AutoPunditz Take
In September 2026, India's passenger vehicle industry saw a 20.9% year-on-year increase in domestic wholesale dispatches, with a 3.6% sequential rise, indicating continued manufacturer momentum.
Maruti Suzuki strengthened its market leadership with significant volume and market share increases. Kia also outperformed the industry, expanding its domestic presence. Tata Motors and Mahindra experienced healthy double-digit growth but faced market share losses due to competition. Hyundai's volumes improved but lagged behind the industry average.
Conversely, Toyota, Honda, Renault, and Volkswagen reported year-on-year declines, highlighting varied manufacturer performance.
These figures reflect wholesale dispatches, not retail registrations or deliveries. Higher dispatches may indicate anticipated demand, inventory replenishment, or production availability. Retail trends and inventory levels will be crucial for evaluating how these volumes translate into consumer demand.
September closed with approximately 4.58 lakh units dispatched, showing robust growth. Maruti Suzuki dominated, while Kia and Nissan showed notable growth. Tata Motors and Mahindra remained leading manufacturers, with Hyundai in fourth place.
The coming months will be key to assessing whether retail demand sustains the industry's strong dispatch momentum and if manufacturers can convert higher volumes into lasting market share gains.